


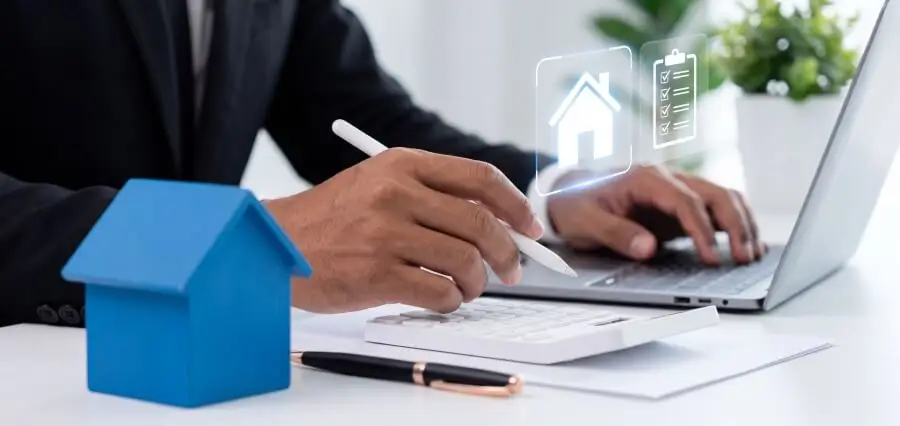
When it comes to property management accounting and bookkeeping, it’ll usually include tracking tenant rent payments, facility maintenance, and owner distributions for a bunch of apartments in multi-unit buildings. At-first, most of these property managers will handle this type of work in-house, yet as their real estate portfolios grow, their workloads increase, and that’s when financial errors become a bit more common. However, opting to outsource the accounting and bookkeeping tasks to specialists, it can really cut down their overall costs while improving financial reporting and their books.
One very clear way that outsourcing accounting work to specialists is that it can quickly reduce your internal expenses by lowering the headcount of your internal staff and with that, overall overhead. Hiring a bookkeeper or a staff accountant on a full-time basis internally means you’re going to also be covering their salaries, benefits, training, licenses, office space, and other overhead, like recruiting costs. Yet, for smaller property management firms, these other fixed costs can add up quickly, especially if the volume of rental transactions fluctuates with seasonal vacancies or new acquisitions. Outsourced accounting companies usually charge their clients on a per-property or transaction type basis monthly. Plus, the property management companies usually just pay for the work that’s only been completed, which helps to keep their overhead lower, flexible, and a bit easier to forecast.
Outsourced accounting specialists typically utilize more modern financial processes and systems that help prevent costly errors, which can really hit your bottom line. Whether they’re incorrect rent ledgers, misclassified expenses, or late tax filings, these mistakes can trigger a variety of hefty penalties, tenant disputes, or severe legal claims. Then come the big attorney fees to represent you, which is another major expense, but is totally preventable. When it comes to working with more experienced property accounting teams, they already know several of the most common pitfalls – especially when it comes to handling security deposits, CAM reconciliations, or depreciation schedules. These accounting pros will apply more consistent, proven processes that just work. By opting for this path, your company can count on fewer corrections and owner complaints that will quickly translate into spending much less time on cleanup work, while lowering your risks of taking on serious financial losses.
The savings on overall time management really matters a lot as well. Property managers that need to process many invoices, reconcile bank accounts, and prepare monthly reports themselves will often need to sacrifice dozens of hours monthly that could be better spent on leasing, property maintenance, or improving their tenant relations. These types of activities tend to generate more revenue than internal bookkeeping tasks ever could. When the numbers side of things moves over to a far more experienced outsourced accounting services provider, property management companies can better focus on their core operations, which can directly affect increased occupancy and property values. The results realized are often higher income streams and overall profits without seeing a major rise in administrative payrolls.
Access to more modern tech stacks and software tools is another contributing factor to getting more successful outcomes. Professional accounting firms usually invest pretty heavily into specialized accounting and bookkeeping software that’s designed specifically for property management companies. These tools typically have features like automated rent rolls, online owner portals, and real-time reporting dashboards that keep everyone on track. For the property managers that try to buy and maintain the same type of software and tools internally will require having separate subscriptions, added IT support, and keeping up with ongoing software updates. It’s just another layer of work and costs to factor in, which all compound throughout the year. Choosing to outsource your accounting tasks helps reduce those added tech costs, while property managers can benefit greatly from advanced systems without carrying on the full price tag.
The many requirements for tax and labor law compliance continue to change yearly at the state and federal levels too. Tax rules, local landlord and tenant laws, along with updates to GAAP reporting standards for HOAs or commercial properties tend to shift quite regularly. While the demands on owners to keep internal staff current on these changes often requires continuous training, many hours of research, and time spent. Accounting experts monitor and analyze these ongoing updates in part of their work and apply them as needed for you. This type of service really helps reduce the chances of getting hit with several non-compliance fines and will help you avoid the cost of having to hire temporary financial consultants when regulations change.
The flexibility and scalability will often provide even further savings. For example, a property management company that adds ten or even fifty new units can quickly expand their financial support almost immediately just by using an outsourced accounting firm. Try to hire a few new staff internally to accommodate? Think again. The process for hiring and onboarding new staff internally can take you weeks (or months) to find the right people for the job. Plus, it may leave major gaps throughout your operations during that transition period, however long it goes. When a property portfolio shrinks, the outsourced accounting firm you have onboard can easily adjust their level of services down without having to take on any severance costs or underutilized employees. This ability to match your accounting capacity to actual transaction volume helps to keep your business expenses better aligned with your revenue.
Some property managers worry about losing some or most control, let alone facing communication delays. By having very clear and concise service agreements that define the reporting deadlines, their response times, and data access, it’ll better address those concerns head-on from the start. Ensuring you have regular status reviews and team meetings, along with utilizing online collaboration platforms like Slack will help keep all the key players up-to-date in real-time. In practice, many property managers tend to find that the structured processes of working with a more specialized accounting firm actually improves their overall transparency compared to informal methods internally.
When it comes down to comparing the overall costs, you’ll quickly see that outsourcing accounting to specialists becomes really attractive once a portfolio reaches a certain size. This is commonly seen when portfolios grow to having around 50 to 100 units, although the exact point depends on local wage levels and transaction complexities. If the units managed are below that threshold, having simpler spreadsheets for bookkeeping may still work out okay for the time-being though. However, above that threshold, and the combination of reduced fixed costs, fewer accounting errors, better tech stacks, and the amount of recovered time for management can produce very measurable savings.
Outsourcing your property management accounting to experts isn’t a universal solution for all firms, but for many, it removes a growing administrative burden and replaces it with more predictable, specialized financial support. The benefits realized come less from dramatic rate cuts and more from eliminating several hidden costs, such as overtime, staff training, expensive software, accounting errors, and diverted attention. These often accumulate and compound a lot when your accounting functions stay entirely in-house.
If you’re running and operating a property management company that’s looking to increase your efficiencies, save on the overhead of internal staff hires and/or expensive financial mistakes, outsourcing your accounting work to experts may be the way to go. And, it’s something to really consider now or in the future for the good of your business.