


A person asking about a mortgage may arrive with a simple question: What financing options are available? The answer depends on more than a product list. Someone purchasing a first home may be concerned about monthly obligations and unfamiliar paperwork, while another borrower may be thinking about a move, a different property, or a longer-term financial plan. An immediate explanation of every available option may miss the concern that brought the person into the conversation.
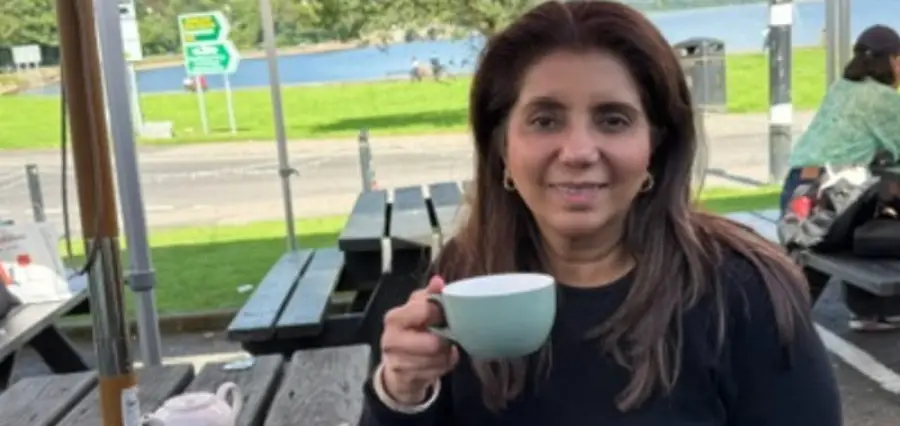
After 27 years in mortgage banking, Shaleen Mahtani has come to value a different starting point. Early in her career, she was eager to share everything she could offer clients and professional contacts. Experience led her to a more personal question: “How can I help?” Her shift offers a lesson about communication in financial services and beyond.
From Explaining Everything to Asking Better Questions
Beginning a career in a specialized field often comes with a desire to demonstrate knowledge. Mortgage professionals learn about financing requirements, documentation, timelines, and the many decisions involved in a property purchase. Eagerness to help can lead to overexplaining.
Mahtani has described doing just that with both clients and referral partners. Over time, she recognized that individuals do not arrive with identical questions or circumstances. A comprehensive presentation may sound informative but leave the most important concern unanswered. Her evolving approach is to listen first, then determine what information or next step is actually relevant. The change was about asking better questions.
Listening Is a Practical Mortgage Banking Skill
Careful listening can reveal details that a client’s opening question does not. A person asking how quickly a mortgage can move forward may be concerned about an approaching relocation. Someone asking about payments may be trying to understand the effect of homeownership on other financial responsibilities. These hypothetical situations show why context matters.
A useful discussion can explore a borrower’s objectives, preferred timing, questions about costs, and level of familiarity with the process. The professional still must consider documented financial information, lender requirements, and applicable rules when discussing possible financing. Listening does not replace eligibility analysis. It identifies what needs explaining before decisions are made.
What “How Can I Help?” Really Means
Mahtani’s guiding question is short, but its value depends on what happens afterward. “How can I help?” invites a person to describe priorities in their own words rather than respond to a ready-made presentation. It changes the initial emphasis from the professional’s offerings to the situation of the person seeking assistance.
That approach also requires patience. An answer may reveal a question that needs further clarification, an expectation that needs discussion, or a concern that cannot be resolved immediately. Helpful communication is not the same as saying yes to every request. Sometimes it means describing limits, explaining what information is missing, or acknowledging that an outcome depends on factors outside anyone’s control. The question becomes meaningful through genuine attention and appropriate follow-through, not through repetition alone.
Understanding the Person Behind the Financing Decision
Mortgage discussions often connect to significant life decisions. Housing preferences, employment circumstances, relocation plans, and family priorities may shape what someone needs to understand. For a first-time homebuyer, unfamiliar terms can make the process feel intimidating. An experienced buyer may already know the basics and want to concentrate on a narrower set of questions.
In reflecting on her career, Mahtani has spoken about the nervousness and excitement she has encountered among people purchasing their first homes. She has also described relationships that continued as clients later considered other properties, with some eventually introducing the next generation to her. These are her recollections, not independently verified outcomes. They help explain why she sees mortgage banking as a relationship-oriented profession rather than merely a sequence of transactions.
Referral Partners Need Individual Attention, Too
The same principles apply when mortgage professionals work with real estate agents and other referral partners. Those relationships involve different responsibilities, schedules, and expectations. One professional may want brief updates at defined milestones, while another may prefer more detailed explanations when a question arises. Assuming everyone communicates the same way can introduce avoidable friction.
Shaleen Mahtani’s approach to mortgage banking includes learning what referral partners need before describing what she can provide. That may involve clarifying communication preferences, understanding an individual partner’s priorities, and being realistic about the information that can be shared. Confidentiality and professional boundaries remain essential. Good relationships depend on reliability, but reliability also means distinguishing a reasonable commitment from a promise that cannot be guaranteed.
Personalizing Communication Without Complicating It
Clear communication is not necessarily lengthy communication. A first-time buyer may appreciate an explanation of basic terminology, while someone familiar with the process may prefer a concise summary of outstanding items. Both deserve accurate information, presented in ways they can use.
Patience also allows space for follow-up questions. A professional can check whether an explanation made sense, identify areas of confusion, and avoid filling every silence with more technical detail. Financial terminology can make decisions feel complicated. Personalized guidance should help people understand their options without implying that a particular product fits everyone or that approval is assured.
Trust Develops Beyond the First Conversation
An encouraging introduction can create a positive impression, but professional trust usually takes longer to establish. Clients and referral partners notice whether calls are returned, updates are understandable, and difficult questions receive candid answers. Consistency matters particularly when timelines change or additional documentation becomes necessary, because uncertainty can test the quality of communication.
Shaleen Mahtani on building client trust centers on genuine interest rather than an immediate sales pitch. Her account suggests a willingness to understand goals before discussing possibilities, then continue treating people as individuals as the relationship develops. It guarantees neither financing nor referrals, but supports informed conversations and realistic expectations.
How Experience Changes the Meaning of Good Service
Mahtani began her mortgage banking career in 1999 and describes 27 years of experience. Her reflection on listening illustrates how professional judgment can develop over time. Product knowledge remains important, but expertise is more useful when paired with the ability to recognize what another person is asking, what they may not yet know to ask, and when further explanation is appropriate.
That change does not mean early-career professionals are poor listeners or experienced professionals automatically communicate well. It shows the value of reassessing habits that once seemed helpful. Improvement begins by noticing when explanations overwhelm or assumptions replace questions. The willingness to adjust is itself a meaningful aspect of financial services leadership.
A Lesson for Work Beyond Mortgage Lending
The temptation to lead with expertise exists in many professions. Consultants, healthcare administrators, service providers, and business owners may all begin meetings by explaining solutions before determining what problem the other person hopes to solve. Listening first does not eliminate the need for specialized knowledge. It helps apply that knowledge more precisely.
Mahtani’s experience offers a modest but useful reminder: curiosity is part of good service. Asking thoughtful questions, respecting different communication preferences, and admitting when more information is needed can make interactions more productive. Those habits require practice. Meaningful relationships are built when people feel heard and can rely on the information they receive.
The Question That Comes Before the Answer
The contrast between Mahtani’s early enthusiasm to explain everything and her current preference for listening captures an important part of professional growth. After decades in mortgage banking, she does not describe relationship-building as a matter of delivering the longest presentation or having an immediate answer to every question. She places greater value on understanding the person, the purpose of the conversation, and the next step that would be genuinely useful.
“How can I help?” is therefore more than a courteous opening. Asked sincerely, and followed by careful attention, it makes room for the needs and priorities that a product-focused discussion might overlook. In mortgage banking, where decisions involve both financial requirements and personal goals, that willingness to listen can be the beginning of a more meaningful professional relationship.